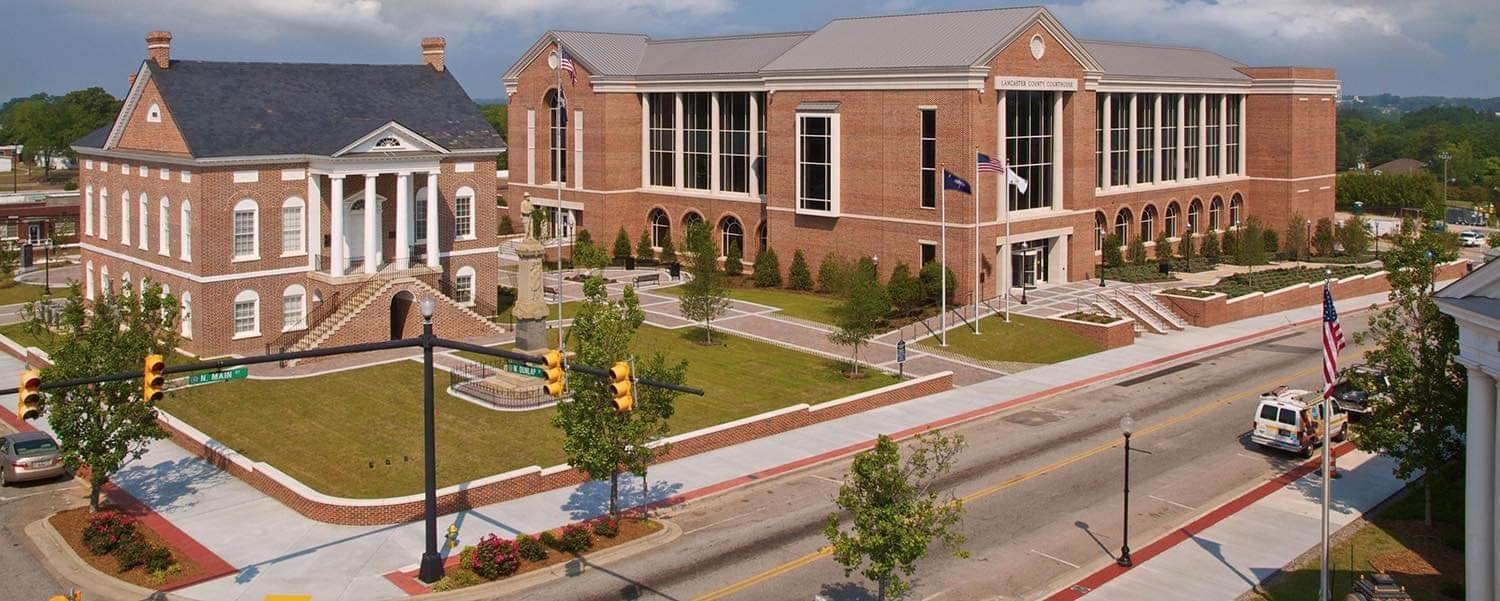
HFC Insurance is located in Lancaster SC providing insurance solutions to our local residence.

Home Insurance in Lancaster, SC

QUICK ANSWER  —  A standard homeowners policy in Lancaster, SC covers five things: your dwelling, other structures, personal property, liability, and loss of use. Two details decide whether it actually holds up here — whether your dwelling limit reflects what it would cost to rebuild at today’s construction prices, and whether your roof is settled at replacement cost or actual cash value. Flood damage is not included in a homeowners policy and takes a separate one. HFC Insurance is an independent agency on Main Street in Lancaster; we compare South Carolina-licensed carriers and check those details before you sign. Call 803-286-1161.

Are you ready for a home insurance quote? Click below.

Most homeowners in Lancaster find out what their policy actually says on the worst possible day — after the storm, after the fire, standing in the yard with an adjuster. By then the details are settled. The time to read them is now, while the choices are still yours.

Home insurance in Lancaster, SC isn’t complicated so much as it is easy to get slightly wrong. A policy can look complete on the declarations page and still leave a six-figure gap. Here’s where those gaps tend to sit for Lancaster County homeowners, and what to check.
The Importance of Local Knowledge in Assessing Home Insurance Needs

Picture yourself navigating through a dense forest with only a vague map in your hands. Now imagine a local guide stepping in—someone who knows every hidden path and secret corner. Suddenly, the journey feels safer and more certain. That’s exactly what it’s like when you work with a local insurance agent to navigate the often confusing world of home insurance. In the maze of coverage options, policy details, and potential risks, local expertise isn’t just helpful—it’s essential.

In today’s rapidly changing environment, where local regulations shift and natural risks evolve, having an expert who understands the terrain can make all the difference. That’s what we’ll explore today: the undeniable value of local guidance in building a home insurance policy that’s not only adequate but perfectly tailored to your needs. If you are looking for car insurance in Lancaster SC and want to maximize your protection while saving more, consider bundling your home coverage with your car insurance.

What does home insurance cover in Lancaster, SC?

A standard homeowners policy is built from five parts:

  • The structure itself — walls, roof, foundation, built-in systems.
  • Other structures. Detached garage, fence, shed, workshop.
  • Personal property. What’s inside — furniture, clothing, electronics, tools.
  • If someone is injured on your property, or you damage someone else’s.
  • Loss of use. Somewhere to stay while your home is repaired.

That’s the frame. The dollar amounts inside it are where policies quietly diverge — and where two homes on the same Lancaster street can end up with very different outcomes after the same storm.

Is your home insured for what it would cost to rebuild today?

This is the single most common gap we find, and it has almost nothing to do with your home’s market value.

Your dwelling limit should reflect replacement cost — what a builder would charge to rebuild your house from the slab up, at current labor and material prices. Construction costs across the Carolinas have climbed substantially in recent years. If your dwelling limit was set when you bought the house and it hasn’t been reviewed since, there’s a reasonable chance it’s behind.

The consequence is sharper than most people expect. Many policies carry a coinsurance provision: if your dwelling coverage falls below roughly 80% of the actual rebuild cost, the carrier can reduce a partial claim payout proportionally — not just on total losses, but on the kitchen fire too. You can be underinsured and current on every premium at the same time. A rebuild-cost review takes a few minutes and is worth doing at renewal.

Is your roof covered at replacement cost or actual cash value?

Here’s the one that surprises people, and it’s worth checking on your policy this week.

Your house can be insured at replacement cost while your roof is settled at actual cash value — in the same policy. Actual cash value factors in depreciation. On a twenty-year-old roof, that can mean a claim check covering a fraction of what a new roof costs, with the rest coming out of your pocket.

Carriers across South Carolina have leaned harder on this in recent years, particularly for older roofs. Some apply ACV settlement past a certain roof age, some tighten eligibility, and some decline the risk. Hail and straight-line winds from summer thunderstorms are a genuine exposure in Lancaster County, so the roof line on your declarations page deserves a look. Find the section that addresses roof settlement and see which term appears. If it says actual cash value, you have a decision to make — and options worth comparing.

Do you have a separate wind and hail deductible?

Coastal South Carolina policies commonly carry percentage-based wind, hail, or named-storm deductibles — 1% to 5% of the dwelling limit, which on a $400,000 home can mean thousands before coverage starts. Inland, Lancaster County homeowners more often have a flat all-perils deductible, which is the friendlier structure.

That said, deductible structures vary by carrier, and some apply a separate wind and hail deductible well inland. Worth confirming which one you have rather than assuming. It changes what a hail claim actually puts back in your hands.

Does homeowners insurance cover flood damage?

No. Flood is excluded from standard homeowners policies and requires separate coverage, through the National Flood Insurance Program or a private carrier.

People hear “Lancaster is inland” and stop there. But flooding follows creeks, drainage, and pavement, not the coastline, and the county’s growth has added a lot of new impervious surface. Being outside a mapped high-risk flood zone lowers your odds; it doesn’t remove them, and it usually lowers the premium too. Water backing up through a drain or sump is a different exclusion again, covered by a water-backup endorsement rather than flood insurance. Two separate gaps, two separate fixes.

Why work with a local agent instead of buying online?

Buying homeowners insurance from a form is like navigating unfamiliar country with a rough map. It gets you moving in roughly the right direction. It doesn’t tell you where the ground gives way.

A local agent knows the terrain because they work it. We know what Lancaster County construction costs look like right now, which carriers are writing older roofs and which are pulling back, and what a home in Indian Land needs compared to one off Highway 9. We ask about the workshop out back, the finished bonus room, the jewelry that’s worth more than the sublimit — the things a quote form doesn’t think to ask.

Because HFC is an independent agency, we compare South Carolina-licensed carriers rather than fitting you into one company’s box. And when you file a claim, you get a person on Main Street who knows your policy, not a queue.

How HFC Insurance helps Lancaster homeowners

  • Run a rebuild-cost review so your dwelling limit reflects today’s construction costs.
  • Check how your roof is settled — and compare carriers if it’s written at actual cash value.
  • Explain your deductible structure before storm season, not after.
  • Flag what a homeowners policy leaves out — flood and water backup are separate, and we’ll tell you where you stand.
  • Stand with you at claim time when you file, from an office you can walk into.

A policy review costs you nothing but the time. Most of the gaps above are found in about fifteen minutes.

Call HFC Insurance at 803-286-1161 or stop by our office at 304 N Main St, Lancaster, SC. We’re an independent insurance agency right here in Lancaster County — and we handle your auto, business, and Medicare coverage too.

M Smith Testimonial about the great service from HFC Insurance in Lancaster SC
Testimonial for HFC Insurance

Benefits You Can Expect

“The HFC Insurance team is always a pleasure to work with! They have been extremely helpful, knowledgeable, and patient since day one of doing business with them. They are also responsive to any questions. Look forward to working with them in the years to come and highly recommend their services!”

Robert Pellegrino

Frequently Asked Questions About Home Insurance in Lancaster, SC

How much does home insurance cost in Lancaster, SC?

There’s no single number. Premiums depend on your home’s rebuild cost, age, roof condition, deductible, claims history, and the carrier. An independent agency can compare several South Carolina-licensed carriers on the same coverage baseline so you’re comparing like for like rather than shopping on price alone.

Does homeowners insurance cover flood damage in South Carolina?

No. Flood is excluded from standard homeowners policies and requires a separate policy through the National Flood Insurance Program or a private carrier. Being outside a mapped high-risk zone usually means a lower premium, not zero risk.

Why is my roof only covered at actual cash value?

Some carriers settle older roofs on an actual cash value basis, which factors in depreciation and can leave a large gap between the claim check and the cost of a new roof. It’s often tied to roof age. Check the roof settlement language on your declarations page — other carriers may still offer replacement cost.

How much dwelling coverage do I need on my Lancaster home?

Enough to rebuild at current construction costs, which is different from your home’s market value or tax assessment. Many policies reduce partial claim payouts if dwelling coverage falls below roughly 80% of the rebuild cost, so an outdated limit can affect ordinary claims, not just total losses.

Do Lancaster County homeowners have a separate wind and hail deductible?

Often not — percentage-based wind, hail, and named-storm deductibles are more common on the South Carolina coast, while inland policies more often carry a flat all-perils deductible. It varies by carrier, so confirm which structure your policy uses.

HFC Insurance

304 N Main St, Lancaster SC 29720

803-286-1161